Chapter 13 - The Price of Coming Home
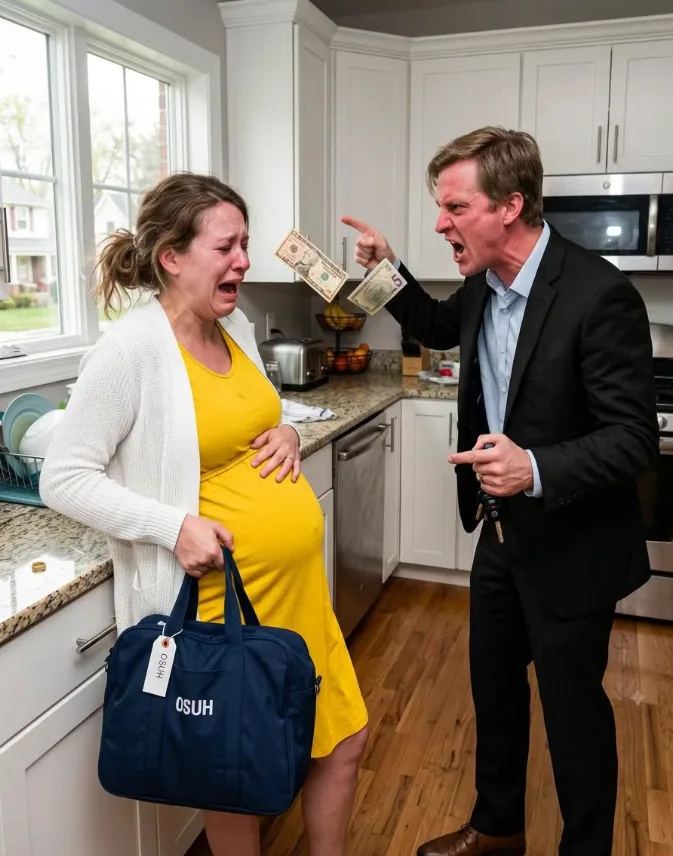
The insurance scare became real for forty-eight hours before coverage was restored.
During that window, the hospital billing office called me twice.
The first representative was polite.
The second sounded like she was reading from a script designed to make a five-figure number feel ordinary.
"The current patient responsibility is thirty-four thousand six hundred and twelve dollars, pending insurance resolution."
I gripped the edge of Rachel's counter.
"I do not have thirty-four thousand dollars."
"We understand claims can be corrected."
"My husband removed me after I gave birth."
The representative became quiet.
"I am sorry."
It was a small human reaction, and I nearly cried because of it.
She placed a temporary hold on collection activity while the claim was reviewed.
After the call, I opened my new checking account.
There was less than four thousand dollars in it.
For years, Derek had told me insurance was one of the reasons I could not afford to leave.
Now he was proving how intentionally he had chosen that leverage.
I imagined being alone without Rachel.
No spare bedroom.
No borrowed car.
No attorney referral.
No one to sit beside me while a billing office said thirty-four thousand dollars.
The thought frightened me more than any courtroom.
"This is why people go back," I told Rachel.
She looked up from washing bottles.
"What?"
"Not because they suddenly forget what happened."
I turned the laptop toward her.
"Because eventually every door out has a bill attached to it."
Rachel dried her hands.
"Then we keep opening doors."
The sentence was simple.
It was also the reason I did not call Derek and accept his offer that afternoon.
The bank fraud specialist contacted me again the next day.
She asked whether I had ever signed blank loan forms for Derek.
I had not.
She asked whether I had ever given Melissa authority to acknowledge a signature remotely.
I had not.
She asked whether I recognized the phone number listed beside my name on the loan application.
I did.
It was Derek's secondary work phone.
The application had not only used my stolen signature.
It had replaced my real contact information with a number he controlled.
Any verification call would have gone to him.
The email address was another variation of my name that forwarded to his account.
The design was so deliberate that I stopped feeling shocked.
I felt tired.
"How many steps does fraud need before people stop calling it a misunderstanding?"
I asked the specialist.
She paused.
"That determination is for our legal team."
It was the correct answer.
It still made me laugh without humor.
Melissa's attorney later confirmed that she had surrendered her notary journal for investigation.
The journal entry for my supposed appearance listed 4:10 p.m.
At 4:10 p.m. that day, my obstetric office had a check-in record showing I was still there.
A parking garage exit record showed my car leaving at 4:37.
The lender's office was nearly forty minutes away.
Even if I had wanted to attend, I could not have been in both places.
For once, time itself testified for me.
Michael added the medical check-in and garage record to our evidence file.
"This is why we do not rely only on memory," he said.
I thought about all the times Derek told me I remembered arguments incorrectly.
Receipts, timestamps, metadata, call logs, and camera footage had begun surrounding my memory like witnesses.
I no longer needed every person to trust my feelings.
The facts had clocks attached.
The emergency insurance motion was heard two days later.
Derek's attorney called the removal request an administrative misunderstanding.
Michael submitted the parenting-app message.
YOU SHOULD HAVE THOUGHT ABOUT INSURANCE BEFORE RUNNING AWAY.
The judge read it twice.
Then she asked Derek whether he wrote it.
"Yes."
"What did you mean?"
Derek looked toward his attorney.
The judge waited.
"I was frustrated."
"That does not answer my question."
"I meant that leaving had consequences."
The judge's expression hardened.
"Health insurance for a newborn is not a punishment mechanism."
No one spoke.
The court ordered both my coverage and Emily's coverage maintained pending further order.
Derek was prohibited from altering benefits, beneficiaries, or insurance elections without written agreement or court permission.
It should have felt like victory.
Instead, every court order felt like a fence built after Derek already ran through the yard.
I kept wondering what he would try next.
He answered that question sooner than expected.
Three days later, a courier delivered a thick envelope to Rachel's house.
Inside was a handwritten letter from Derek.
No lawyer letterhead.
No court platform.
He had found another route around the communication order.
Claire,
I know you think everyone is against you right now.
I read the first sentence twice.
Not I am sorry.
Not I was wrong.
I know you think.
Even on paper, he needed my reality to be a perception problem.
The letter continued for seven pages.
Derek described our first apartment.
Our honeymoon in Charleston.
The night we adopted our old dog, Murphy.
The day we learned I was pregnant.
He wrote about the life we planned.
For several paragraphs, I almost recognized him.
Then the terms appeared.
If I returned to Columbus, he would withdraw his request for expanded custody.
He would "handle" the disputed credit card.
He would "make sure" the home equity issue did not affect me.
He would pay for a nanny when I returned to work.
He would restore my access to every account.
All he wanted was for me to stop listening to Rachel and "outsiders who profit from divorce."
The final page contained one sentence underlined twice.
YOU CAN STILL COME HOME BEFORE THERE IS NOTHING LEFT TO COME HOME TO.
Rachel read the letter in silence.
"He is threatening the house."
"Or the marriage."
"Same thing to him."
I sent the letter to Michael.
He filed a notice documenting unauthorized direct contact.
Derek's attorney apologized and claimed he had not approved it.
For once, I believed him.
The forensic accountant's preliminary report arrived that week.
It was forty-three pages long.
I understood maybe half of it.
Michael translated the important parts.
Derek had lost approximately $211,000 over eighteen months through leveraged investments and a private real estate venture.
He funded part of the losses with the home equity line.
He covered part with transfers from our joint account.
He used the fraudulent credit card for personal spending while preserving cash for margin calls.
He paid for travel with Lauren on the card in my name.
He moved money between accounts in ways that made the household balance appear lower than our income suggested.
Then he blamed me for "spending too much" whenever I asked why savings were not growing.
I remembered standing in a grocery store aisle six months earlier holding two brands of prenatal vitamins.
One cost twelve dollars more.
Derek had made me send him photographs of both labels before he approved the purchase.
At the same time, he was losing tens of thousands of dollars in investments I did not know existed.
The memory made me shake with anger.
"He made me feel irresponsible over vitamins."
Michael looked at me through the video call.
"That is one reason the accounting matters."
The report also found something unexpected.
Derek had opened a safe-deposit box eight months earlier.
The annual fee came from our joint account.
"What is in it?"
"We do not know."
"Can we find out?"
"We can request disclosure."
Derek's attorney claimed the box contained personal family documents.
The judge ordered an inventory through counsel.
One week later, the bank opened the box in the presence of representatives.
There were no jewels.
No cash.
No secret passports.
There were documents.
Copies of our deed.
Copies of my tax returns.
A copy of my driver's license.
My Social Security card.
Old pay stubs.
A photocopy of my signature from the original mortgage closing.
The exact kind of materials someone would need to impersonate me financially.
I stared at the inventory list.
"Why would he store my Social Security card there?"
Rachel asked the obvious question.
"Was your actual card missing?"
I opened the fireproof folder I had taken from the house.
My birth certificate was there.
My passport was there.
The small envelope where I kept my Social Security card was empty.
I had not noticed.
A copy of the card was in Derek's safe-deposit box.
The original was missing.
Michael's voice became very careful.
"When did you last see it?"
"I do not know."
"Months?"
"Maybe years."
I hated admitting that.
Derek always handled tax paperwork.
He always said he was better with details.
I had trusted him with the documents that made it possible for him to become me on paper.
The bank's fraud investigation accelerated after the safe-deposit inventory.
So did the credit card investigation.
Within days, the card issuer provisionally removed the disputed balance from my account and blocked further use.
My credit report showed two additional hard inquiries I did not recognize.
One had not resulted in an account.
The other was still being investigated.
I locked my credit with all three bureaus.
I changed passwords.
I opened a checking account only in my name.
I redirected my maternity payments.
Each small act felt embarrassingly revolutionary.
The first time I logged into an account Derek could not see, I stared at the balance for a full minute.
It was not much.
But it was mine.
At the end of the month, my employer called.
I expected a routine maternity leave question.
Instead, my manager, Denise, sounded uncomfortable.
"Claire, did you authorize Derek to contact Human Resources about extending your leave?"
My body went cold.
"No."
"He called yesterday."
"What did he say?"
"He said you were experiencing postpartum psychiatric complications and would not be able to return on schedule."
I stood so quickly that Emily startled in her bassinet.
"That is false."
"We suspected there might be a misunderstanding because you have been communicating directly with us."
"There is no misunderstanding."
My voice shook.
"My husband has been ordered to stop interfering with my affairs."
Denise went quiet.
"Do you need us to document the call?"
"Yes."
"We will."
After I hung up, I sat on the floor beside Emily's bassinet.
Natalie's words returned.
He called my employer and said I was having a breakdown.
Thirteen years later, Derek had done the same thing to me.
Not similar.
The same.
I called Natalie.
She answered on the second ring.
"He called your job, didn't he?"
Her certainty frightened me.
"How did you know?"
"Because that is what he does when the money stops working."
I closed my eyes.
"What comes after that?"
Natalie was quiet for so long that I checked the phone.
Then she said, "He makes other people afraid for you."
I did not understand until 2:13 the next morning, when blue police lights flashed across Rachel's living room windows.
May you like
Someone had called for an emergency welfare check on Emily and me.